Medicare open enrollment runs through December 7, 2026, for coverage that begins January 1, 2027. As I do every year, here’s a look at the different parts of Medicare, what they cost, and what those costs might look like in your retirement budget.
Part A Hospital Insurance:
Most people pay $0 in monthly premiums for Part A because they or a spouse paid Medicare taxes for at least 40 quarters. If you need to buy Part A, the 2027 monthly premium is $328 if you qualify for the reduced rate or $597 at the full rate. If you’re already receiving Social Security before you turn 65, enrollment is generally automatic. If you’re delaying Social Security, check whether you need to sign up yourself.
The Part A hospital deductible is $1,776 per benefit period in 2027, up from $1,736 in 2026. A benefit period starts when you’re admitted as an inpatient to a hospital or skilled nursing facility. It ends once you’ve gone 60 consecutive days without inpatient hospital care or skilled care in a skilled nursing facility. If you start another benefit period in the same calendar year, you can owe the deductible again.
| Original Medicare Part A costs | 2027 |
|---|---|
| Inpatient hospital deductible per benefit period | $1,776 |
| Hospital coinsurance for days 61–90 | $444 per day |
| Hospital coinsurance for lifetime reserve days | $888 per day |
| Skilled nursing facility coinsurance for days 21–100 | $222 per day |
Medicare gives you 60 lifetime reserve days for hospital stays that go beyond 90 days in a benefit period. For a qualifying skilled nursing facility stay, daily coinsurance is $0 for days 1–20 after any applicable Part A deductible. After day 100, you pay the full cost. That skilled nursing benefit is for qualifying short-term care. Ongoing help with daily activities, such as bathing or dressing, is generally a separate long-term care expense.
Part B Medical Insurance:
Part B generally covers doctor visits, outpatient services, and durable medical equipment. In 2027, the standard monthly premium is $209.40, up from $202.90 in 2026, and the annual deductible is $292, up from $283. With Original Medicare, you generally pay 20% of the Medicare-approved amount for covered services after meeting the deductible. If you’re collecting Social Security, the premium is typically deducted from your benefit. If you’re delaying Social Security, expect a bill for it.
Your premium can be higher if you owe a late enrollment penalty or an income-related surcharge. If you have coverage through your or your spouse’s current employment, check whether you qualify for a Special Enrollment Period before deciding when to enroll. Medicare Savings Programs may help eligible beneficiaries pay their premiums.
The income-related surcharge is called IRMAA, and it can apply to both Part B and Part D. For 2027, Social Security generally looks at 2025 modified adjusted gross income, which for this purpose is adjusted gross income plus tax-exempt interest. IRMAA starts above $112,000 for single filers and $224,000 for married couples filing jointly. The amounts below are monthly and per person, so if both spouses are on Medicare, both can owe the surcharge. If your income has fallen because of a qualifying event such as retirement, you can ask Social Security to review the amount.
| 2025 MAGI, single | 2025 MAGI, married filing jointly | 2027 total Part B monthly premium | 2027 Part D monthly surcharge |
|---|---|---|---|
| $112,000 or less | $224,000 or less | $209.40 | $0 |
| Over $112,000 through $141,000 | Over $224,000 through $282,000 | $293.10 | $15.40 |
| Over $141,000 through $177,000 | Over $282,000 through $354,000 | $418.80 | $39.70 |
| Over $177,000 through $212,000 | Over $354,000 through $424,000 | $544.40 | $64.00 |
| Over $212,000 and under $500,000 | Over $424,000 and under $750,000 | $670.00 | $88.30 |
| $500,000 or more | $750,000 or more | $711.80 | $96.40 |
The Part D surcharge is added to your plan premium. Separate brackets apply if you’re married, file separately, and lived with your spouse at any point during the tax year. See the full CMS premium tables.
There’s also a limited Part B benefit for people whose Medicare coverage based on end-stage renal disease ended 36 months after a kidney transplant and who meet the other eligibility requirements. It covers immunosuppressive drugs, and the standard premium is $125.70 per month in 2027.
Medigap in Massachusetts:
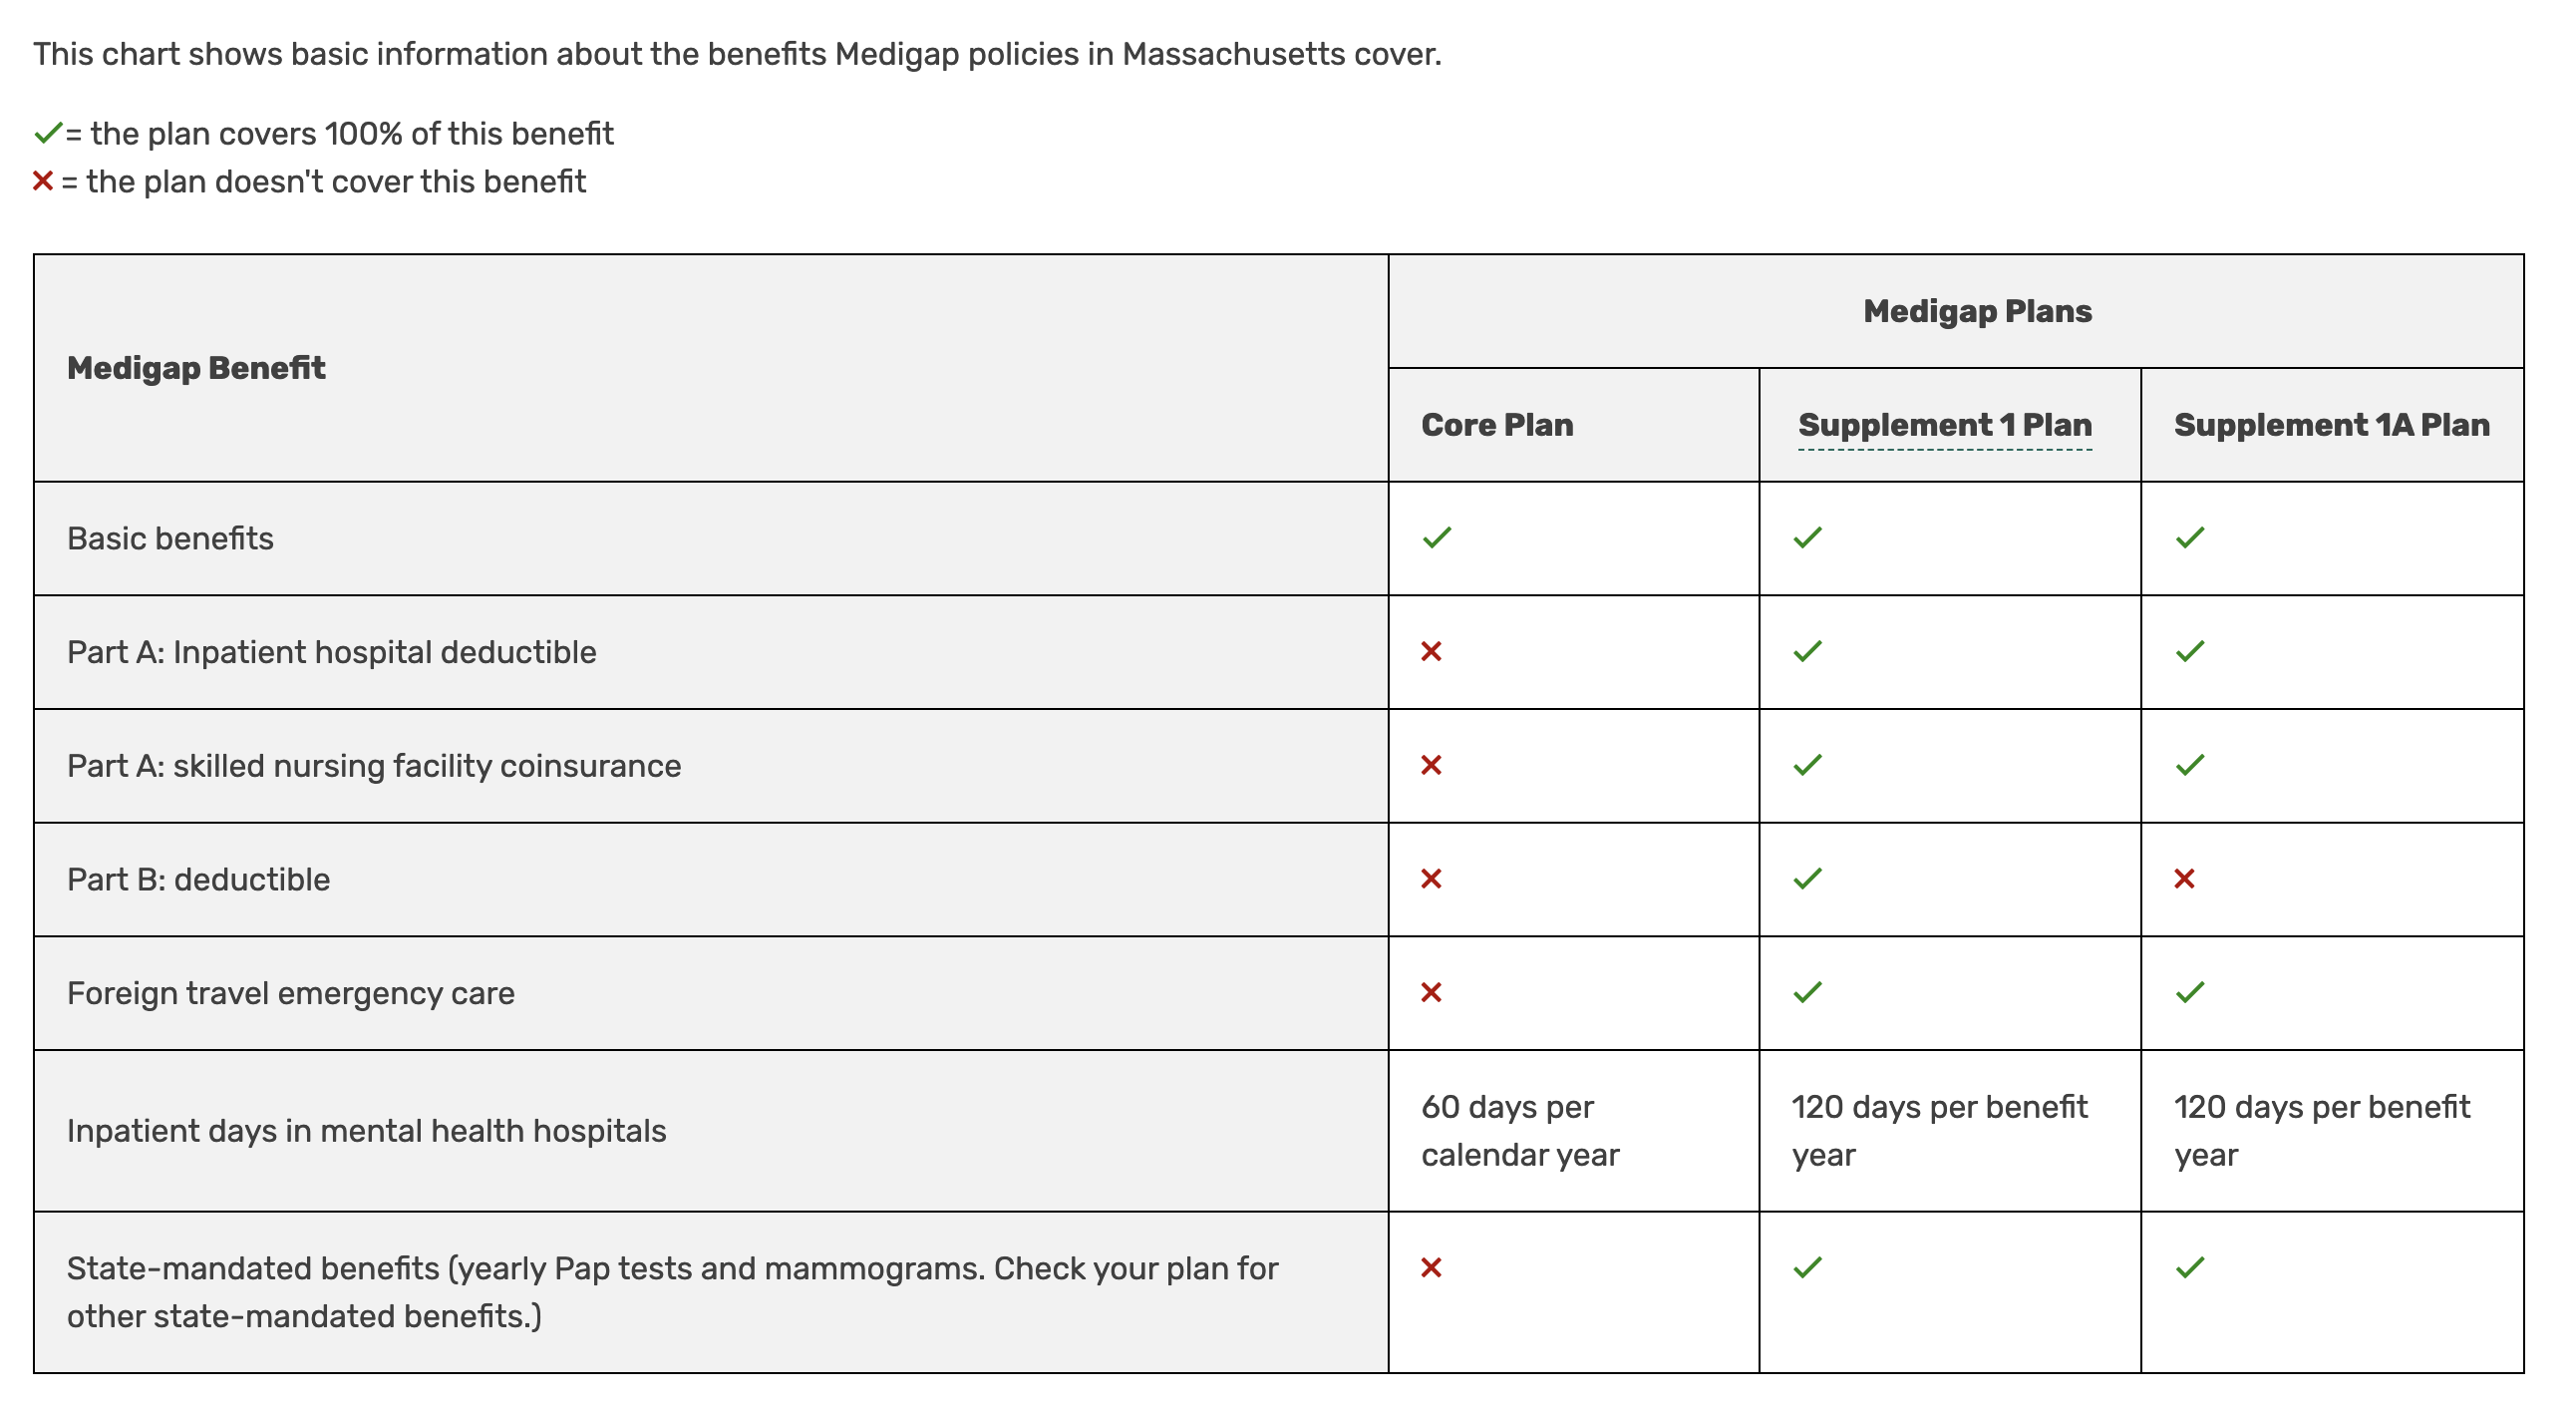
Chart: https://www.medicare.gov/health-drug-plans/medigap/basics/compare-plan-benefits/massachusetts
A Medicare supplement, also called Medigap, helps pay some of the costs left over after Original Medicare pays. Think about that $1,776 hospital deductible and how it could come up more than once in a year. Massachusetts Supplement 1 and Supplement 1A both cover that deductible and the Part A coinsurance for qualifying skilled nursing facility stays. With Original Medicare and Medigap, you can generally see providers nationwide who accept Medicare.
- Supplement 1 covers the Part B deductible and is available only to people who were eligible for Medicare before January 1, 2020.
- Supplement 1A leaves you responsible for the $292 Part B deductible in 2027.
- Core generally has a lower premium and leaves you responsible for costs such as the Part A hospital deductible and skilled nursing facility coinsurance.
If you’re eligible for Supplement 1, compare the annual premium difference with the deductible it covers. For example, Blue Cross Blue Shield of Massachusetts lists Medex Bronze (Supplement 1) at $317.01 per month and Medex Sapphire (Supplement 1A) at $247.15 per month for 2027. That’s about $838 more per year for Supplement 1 to cover a $292 deductible. If you already have Supplement 1 and are considering a switch, check the insurer’s rules first. Compare Massachusetts Medigap premiums.
Part D Prescription Drug Coverage
CMS projects an average $36 monthly premium for stand-alone Part D plans in 2027. Your premium depends on the plan you choose, and the annual deductible can be as high as $700, up from $615 in 2026. Check which of your prescriptions are subject to the deductible, since that can vary by plan and drug tier.
Your annual out-of-pocket costs for covered Part D drugs are capped at $2,400 in 2027, up from $2,100 in 2026. The cap applies to covered drug spending through a stand-alone Part D plan or Medicare Advantage drug coverage. Premiums and prescriptions your plan doesn’t cover are outside the cap. Once you reach it, you pay $0 for covered Part D drugs for the rest of the calendar year.
A month’s supply of each covered insulin product costs $35 or less, and recommended adult vaccines covered under Part D, including shingles, are available with $0 cost sharing. Negotiated Medicare prices for 15 additional Part D drugs take effect January 1, 2027. See the list of drugs and negotiated prices.
Even if you take few prescriptions today, going 63 days or more in a row without Part D or other creditable drug coverage after your initial enrollment period can lead to an ongoing penalty. If you already have a plan, use open enrollment to check your medications, your preferred pharmacy, and your estimated total annual cost. The same plan can change its drug list, pharmacy network, and copays from one year to the next. Read more about choosing a plan during Medicare open enrollment.
Medicare Advantage Plans
Medicare Advantage is another way to get your Part A and Part B benefits through a private insurer. Most plans include prescription drug coverage, and you generally still pay your Part B premium. Depending on the plan, you may need to use a network, get a referral for a specialist, or obtain prior authorization for certain services. Check your preferred doctors and hospitals when comparing plans.
A low monthly premium can make Medicare Advantage appealing. When you compare it with Original Medicare plus a supplement, look at what you’d pay in a year when you actually need more care. Check the hospital copays, coinsurance, and the plan’s annual out-of-pocket maximum for covered medical services. For a PPO, look at both the in-network limit and the combined in- and out-of-network limit. If the plan includes Part D, the $2,400 prescription drug cap is separate from the medical maximum.
What might Medicare cost in 2027?
Here’s an example for one Massachusetts resident with premium-free Part A, the standard Part B premium, Supplement 1A, and a stand-alone Part D plan. I’m using the published Medex Sapphire premium and assuming $20 a month in generic prescription copays. Your drug costs will depend on your medications, plan, and pharmacy.
| Coverage | Monthly cost | Annual cost |
|---|---|---|
| Part A premium | $0 | $0 |
| Standard Part B premium | $209.40 | $2,512.80 |
| Supplement 1A, using Medex Sapphire | $247.15 | $2,965.80 |
| Part D, assuming a $36 premium and $20 in copays | $56.00 | $672.00 |
| Total before any Part B deductible | $512.55 | $6,150.60 |
If you pay the full $292 Part B deductible, the example comes to $6,442.60 for the year, or about $537 per month on average. Your budget could be higher if you owe IRMAA or have additional prescription costs.
If you’re trying to figure out how Medicare fits into your retirement budget, schedule a free consultation with POWWOW.